Many consumers overestimate the credit score needed to qualify for a mortgage, with average guesses around 652, while it’s actually 620 or even lower with new score models. The mortgage industry is evolving, using new models like FICO 10T and VantageScore 4.0. Consulting a loan officer can clarify requirements.
Author Archives: Your@Home Team with Re/Max Results
Confused by Home Price Headlines? Here’s Why.
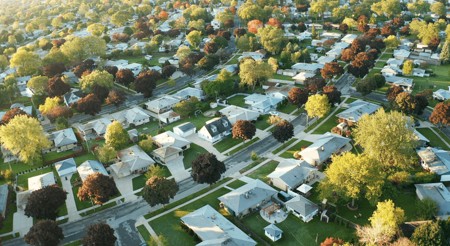
Home prices fluctuate based on location and market conditions. National headlines can misrepresent trends, with current asking prices down due to increased inventory and rising mortgage rates. However, local markets vary significantly. Despite minor declines, major cities show resilience, and values have consistently appreciated over time. Understanding local dynamics is crucial.
Want a More Affordable Home? Don’t Overlook Condos.
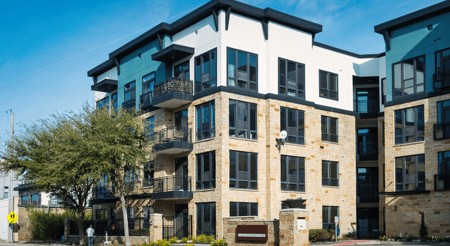
First-time homebuyers often envision traditional houses, but rising prices can make this challenging. Condos offer a more affordable option, typically costing less than single-family homes. Many markets show significant price gaps favoring condos, making them a viable alternative. Exploring these options can help potential buyers enter the market more easily.
Renovate or Relocate? What to Know Before You Decide to Age in Place
As homeowners approach retirement, they face the decision to stay in their beloved homes or move to 55+ communities. Updating homes for aging in place can be costly and noisy, while equity built over the years may finance a new home. Finding the right fit for comfort and convenience is essential.
Data Centers Are Moving Closer to Homes. What Does That Mean for You?
Data centers are increasingly appearing in communities, influencing real estate dynamics. While initial concerns about their impact on home values show no significant effects, factors like local infrastructure and visibility can vary. Data centers may enhance development but also bring noise and resource demands. Buyers and sellers should stay informed about nearby projects.
The Best Time to Buy a Home in 2026 is Almost Here
Considering buying a house this year? While rising mortgage rates present challenges, the period around September 27 to October 3 could offer favorable conditions. Increased inventory, lower prices, and reduced competition enhance buyer prospects. The entire month of October also presents opportunities, so align your strategy to seize the right moment.
The Market Changed. Your Reason for Moving Didn’t.
Many individuals hesitate to move due to hopes of better market conditions, but key life changes often necessitate a move, regardless of the market. With an increasing number of homes for sale, waiting may prolong discomfort. It’s crucial to evaluate whether your current situation meets your needs, as life’s circumstances continually evolve.
The Housing Market Split in 2. Which Side Is Your House On?
The housing market is currently divided by price point. Homes under $250,000 are experiencing slower sales, while those over $750,000 are selling faster due to buyer competition and less sensitivity to interest rates. Effective pricing and presentation are crucial for sellers at all levels to attract potential buyers.
Worried About a Housing Crash? The Numbers Tell a Calmer Story.
A recent Talker Research survey showed that Americans describe 2026 as “stressful.” Despite this, the housing market has stabilized with steady home prices, consistent inventory, and stable mortgage rates between 6% and 7%. This predictability allows buyers and sellers to navigate the market confidently, signaling a healthy housing environment.
Here’s Why Mortgage Rates Are What They Are Right Now
Mortgage rates are influenced by the 10-year treasury yield, with the gap known as the “spread” affecting current rates. Recently, the spread has narrowed, impacting future rate reductions. Currently, mortgage rates are around 6.69%, better than they could be but unlikely to drop significantly soon due to the current spread dynamics.

